Out-of-State Rental Property: Remote Investing Playbook
The Smart Investor’s Guide to Buying Rental Property Out of State: A Remote Investing Playbook
Buying a rental in another state can unlock better cash flow, stronger job markets, and more inventory—without relocating. The challenge is that distance magnifies every small mistake: the wrong neighborhood, a loose contractor bid, a property manager who “sounds fine,” or an inspection report no one translates into a real repair plan. Our team built this guide as a step-by-step operating system for remote rental property investing—so your decisions stay numbers-driven, your local team stays accountable, and your property performs even when you’re hundreds of miles away.
Who out-of-state investing fits (and who should wait)
Remote investing works best when you’re willing to run a repeatable process: market selection → deal screening → team building → acquisition → stabilization. If you value cash flow and you’re comfortable managing by written standards (not vibes), you’re a strong fit.
You should wait if you’re relying on “gut feel” visits, you don’t have meaningful reserves, or you’re unwilling to hire and manage a local team. Distance doesn’t forgive unclear expectations—so the plan only works when the property can be managed by systems: documented criteria, written scopes of work, clear performance metrics, and scheduled check-ins.
Define your “why” up front. Are you prioritizing cash flow, diversification, long-term appreciation, or positioning for a future move? Your target determines your market choice and buy box.
Choose the right market from a distance
Start with numbers, then narrow using on-the-ground realities: tenant demand, typical property-condition issues, insurance trends, and local regulations. Before you fall in love with a “hot” zip code, build a simple buy box you can apply consistently.
Build a simple buy box (and stick to it)
A practical buy box includes: price range, property type, bedroom/bath minimums, year-built range, and a target rent-to-price relationship. It keeps you from chasing every shiny listing and helps your agent and property manager support you with consistent feedback.
Screen markets with public data—then pressure-test expenses
Remote Market Shortlist Scorecard (example framework)
| Factor | What to Check | Why It Matters | Pass/Fail Rule |
|---|---|---|---|
| Rent demand | Vacancy rate, days on market for rentals, major employers | Reduces turnover and extended vacancy loss | Reject markets where vacancies are persistently high vs comparable areas |
| Operating costs | Property taxes, insurance quotes, utilities responsibility, HOA norms | Protects real cash flow (not just pro forma cash flow) | Reject deals that only work with unrealistically low expenses |
| Landlord friendliness | Eviction timelines, notice requirements, rent control/local ordinances | Affects risk and the cost of non-paying tenants | Avoid areas with long timelines unless reserves and screening standards are stronger |
| Housing stock risk | Age of homes, common issues (sewer lines, roofs, foundations), weather exposure | Predicts capex and surprise repairs | Prefer areas with manageable capex profiles and insurability |
| Exit liquidity | Owner-occupant demand, investor demand, lending availability | Improves options when selling or refinancing | Avoid micro-markets where resale depends on a small buyer pool |
Build the local team before buying
Underwrite like a remote owner (real numbers, real reserves)
For tax fundamentals on rental income and expenses, the IRS overview is a solid reference: IRS Publication 527: Residential Rental Property.
Remote due diligence that actually protects the deal
Insurance should be reviewed before closing, not after. Confirm replacement cost, wind/hail exposure, flood zone status, and deductibles. For flood risk basics, use: National Flood Insurance Program (NFIP). Keep every report, bid, comp, and photo in one organized folder so the handoff to management is clean.
Closing to stabilization: the first 90 days
Common remote-investing mistakes to avoid
A practical next step: our complete remote investing guide
If you want a clear, repeatable path to finding, buying, and managing a rental from anywhere, our team put it into a single playbook: The Smart Investor’s Guide to Buying Rental Property Out of State (eBook). You can use it to build your personal buy box, evaluate markets with a scorecard, and create accountability with your local team—not assumptions. Keep it open during underwriting, due diligence, and your first 90 days after closing so the plan doesn’t fall apart after the keys change hands.
If you’re also building a better learning routine (so you actually finish the resources you buy), pair it with Unlock the Page: Your Simple Guide to Getting Motivated to Read More Books.
For broader lending and mortgage education as you compare financing options across states, the CFPB hub is a reliable reference: Consumer Financial Protection Bureau (CFPB): Mortgage resources.
FAQ
Is it realistic to buy and manage a rental property out of state without traveling?
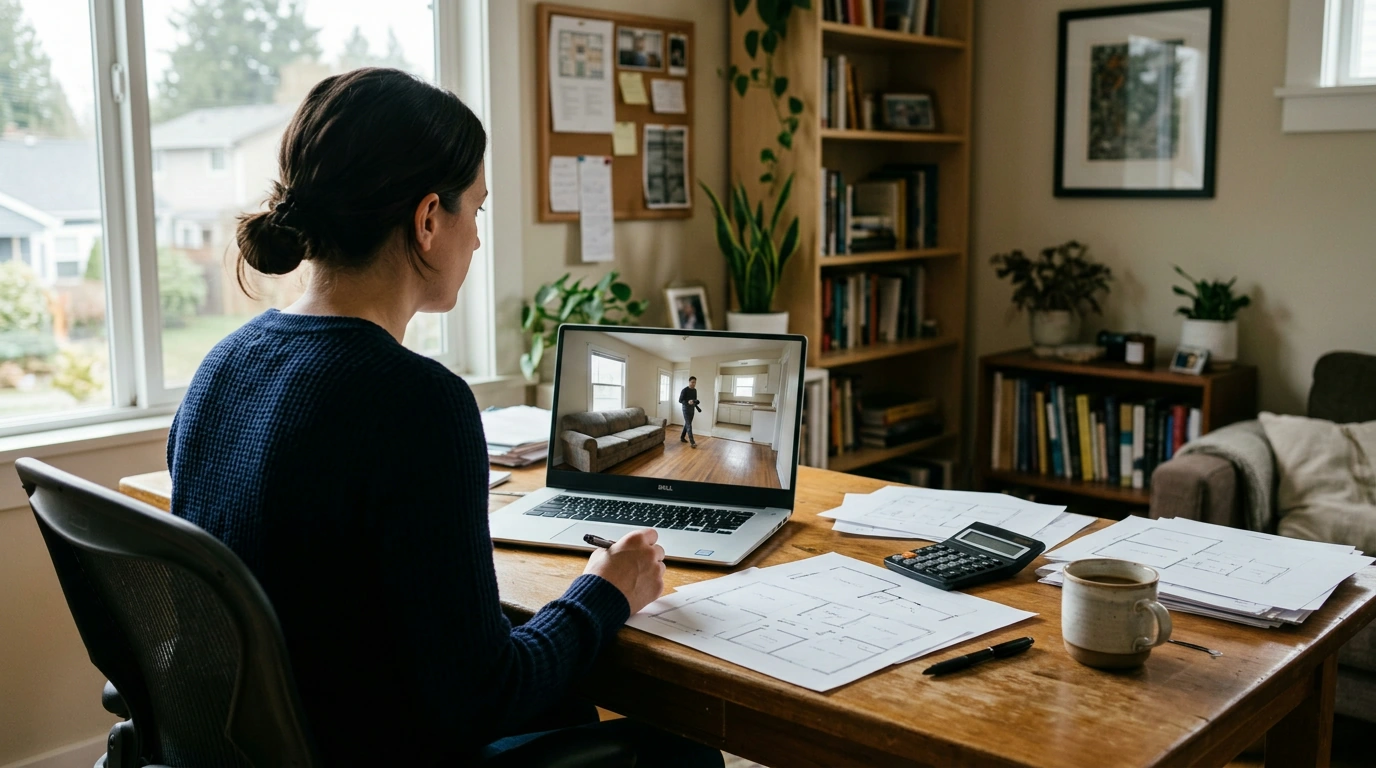
Yes for many rentals, as long as you choose the market with data, vet your local team carefully, and do due diligence with video walkthroughs plus the right third-party inspections. Occasional travel can still be useful for strengthening relationships and scaling, but it isn’t required for every deal.
What’s the most important hire for remote real estate investing?
Your property manager is the most important hire because they control leasing, screening, maintenance coordination, and reporting. Require a sample monthly report, a written screening policy, and clear maintenance controls (approval thresholds, markups, and vendor process) before you commit.
How much cash reserve should be set aside for an out-of-state rental?
A practical framework is: several months of operating expenses plus a vacancy/turnover buffer, plus enough to cover one major system failure (like HVAC or a roof). Increase reserves for older properties, areas with longer eviction timelines, or higher insurance deductibles.


Leave a comment