Make Saving Simpler With an Envelope Checklist
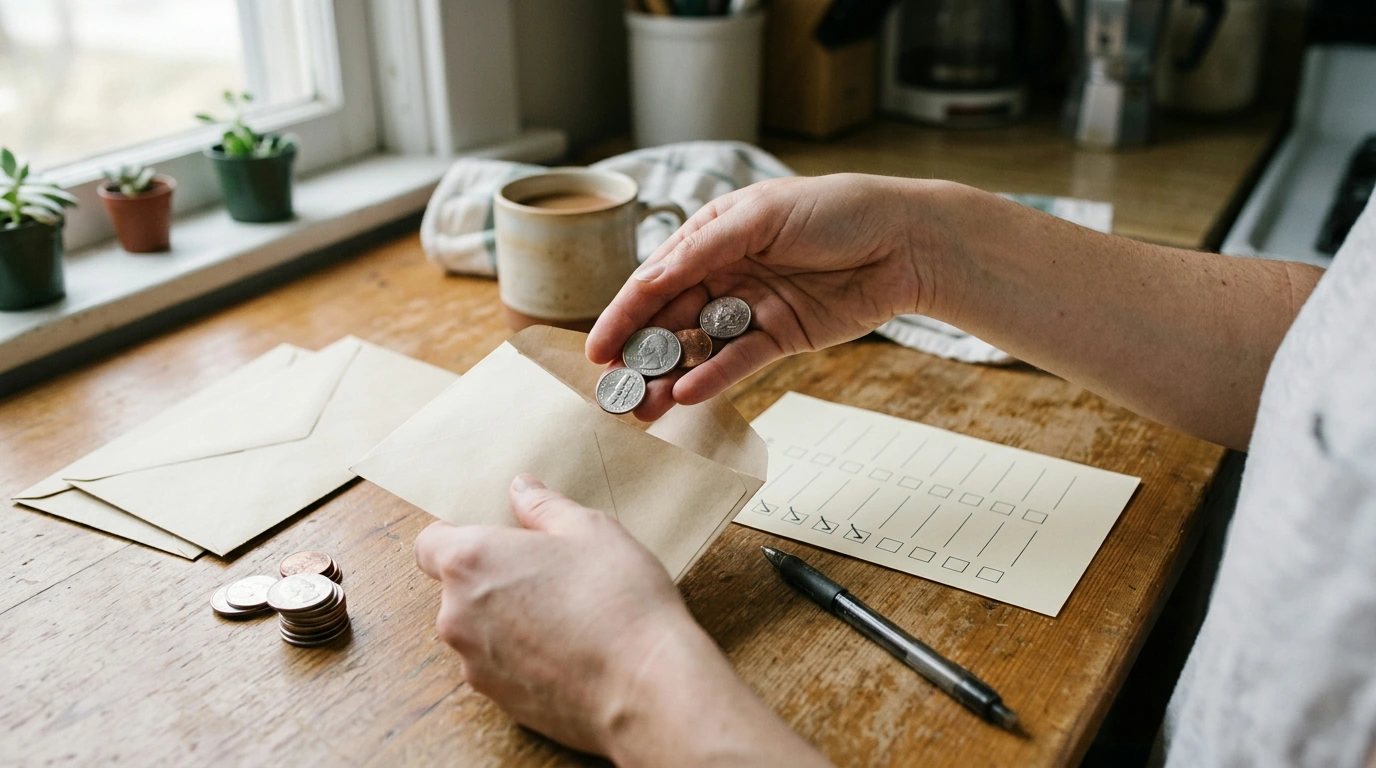
Saving money can start with one small decision: give some of your money a purpose before it gets absorbed into everyday spending. You do not need an elaborate system to begin. A named goal, a manageable contribution, and a regular moment to review your progress can help you build a routine that fits your life.
Our Stuff It & Save It Checklist is a $2.99 printable and digital download you can use alongside an envelope-style savings plan. Here is how to put that plan to work without making your budget feel rigid.
Start with one savings goal
Choose something specific enough that you know what each contribution is for. That might be a future car repair, an emergency cushion, a holiday expense, or a purchase you have already planned. “Save more” can be hard to act on; “set aside money for my next insurance payment” gives your deposits a clear job.
Next, choose a target and a date to revisit it. The date does not have to be a deadline for finishing the goal. It can simply be a reminder to ask whether your contribution still works. If setting aside $20 each payday would leave you short on groceries or a bill, choose a smaller amount. Progress you can sustain is more useful than a target you feel pressured to meet.
A checklist makes your steps visible, but it is not a measure of how quickly you should save. Your income, expenses, and priorities are your own. Marking one achievable deposit is still progress.
Give each envelope a job
With an envelope-style plan, you set aside money for a named purpose instead of treating it as available for general spending. You can put cash in a physical envelope labeled “car maintenance,” for example. If you rarely use cash, you can make a category with the same name in your digital budget and record what you allocate to it. The routine matters more than the format.
Start with one or two goals. Too many envelopes can make every payday feel like a complicated sorting exercise. Once you know what you can comfortably contribute and how often you want to review it, you can decide whether another category would help.
A simple way to set up an envelope-saving routine
| Step | What to do | Keep it manageable |
|---|---|---|
| Choose a purpose | Name the expense or goal the money is for. | Start with one priority. |
| Set an amount | Choose a contribution that fits after essential expenses. | A small amount still counts. |
| Check your progress | Review what you have set aside and mark your progress. | Use a regular day you will remember. |
| Adjust when needed | Change the contribution if your budget changes. | Protect necessities before savings targets. |
If you are unsure what amount is available, look at your budget first. The Consumer Financial Protection Bureau’s budgeting resources and Consumer.gov’s guide to making a budget can help you compare money coming in with expenses going out. Your envelope contribution should come from what you can actually spare, not from money needed for essentials.
Make the checklist part of your routine
A savings plan is easier to revisit when you attach it to something you already do. You might look at your checklist on payday, during a weekly budget review, or when you pay recurring bills. Pick a moment that gives you time to confirm the money is available before you move it.
We offer the Stuff It & Save It Checklist for you if you want a straightforward prompt to keep that routine in view. Use it to note steps you complete, then compare those notes with the cash or account balance where you keep your savings. The download does not automatically track deposits or calculate totals, so record contributions consistently in whatever system you use.
Give yourself credit for completing a step, even if the amount is modest. If you enjoy building routines in other parts of life, our Unlock the Page reading habit guide is another digital download focused on making a personal goal easier to return to. You do not need a new project, though, to make your savings check-in worthwhile.
Keep your budget flexible
Before choosing each contribution, account for housing, food, utilities, transportation, and required debt payments. Saving toward a goal should not mean missing a necessity. If your income varies, you may prefer to decide what to set aside after those obligations are covered rather than promising the same amount every week.
Missed a deposit? Treat it as information, not failure. Perhaps an unexpected expense came up, or the amount you chose was too ambitious. You can resume when you are able, reduce the contribution, or give yourself a longer timeline. Review your goal when your income, expenses, or priorities change, too. An envelope is meant to serve your life—not lock you into an old plan.
When you are ready, choose one purpose and one achievable deposit. Our checklist can give you a place to mark that first step and a reason to come back for the next one.
FAQ
Do I need to use cash envelopes with this checklist?
No. You can use physical cash envelopes or named categories in a digital budget, depending on how you manage money.
How much should I put in a savings envelope?
Choose an amount that fits after essential expenses and required payments. A small contribution you can manage is a good place to start.
What if I miss a week of saving?
Resume when you can, and consider whether a smaller amount or a different schedule would work better. You do not need a perfect streak to keep going.


Leave a comment