How to Check Your Equifax Score & Read the Report
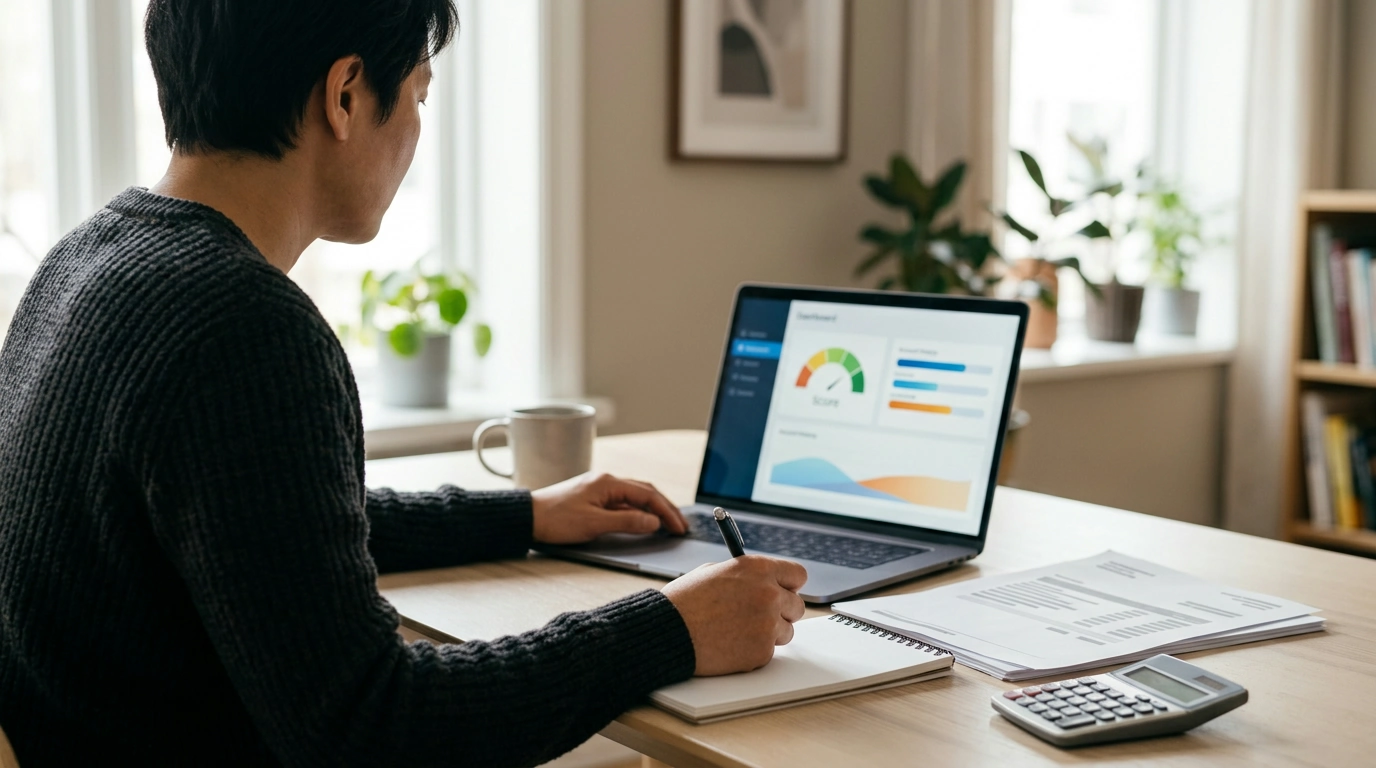
Checking and Understanding Your Equifax Credit Score: A Clear, Step-by-Step Guide (Digital Download)
Credit decisions move fast—rentals, loans, credit cards, even utilities—and your Equifax credit score can be a key part of what lenders see. Our team built this digital download to make Equifax feel less like a black box and more like a checklist: how to check your Equifax credit score, what the numbers typically mean, how to read the details behind the score, and what to do next if something looks off.
What an Equifax credit score is (and what it isn’t)
Your credit score is a snapshot number generated from information in a credit report. It isn’t a permanent “grade,” and it can shift as your report changes—sometimes from month to month.
- Equifax is one of the three major U.S. credit bureaus; a lender may pull Equifax data, another bureau’s data, or more than one.
- A score is different from a credit report: the report is the underlying record (accounts, balances, payment history, inquiries), while the score is the summary output.
- Multiple scoring models exist, so the score you see in one place may not match what a specific lender uses, even when the report data is similar.
Common ways people access Equifax information
| Where you’re checking | What you typically get | Best for | Notes to watch |
|---|---|---|---|
| Equifax (direct) | Access to Equifax-based score/report options (varies by product) | Confirming details at the source | Verify you’re viewing Equifax data (not a different bureau) |
| AnnualCreditReport.com | Credit report (no score) from Equifax and other bureaus | Reviewing accounts, balances, and errors | Free access to reports; scores usually not included |
| Bank/credit card dashboard | Credit score + alerts (model/bureau varies) | Ongoing monitoring | Check which bureau/model is used; updates may lag |
| Lender application pull | Lender’s score and report view | Major credit decisions | You may not see the same number the lender sees |
How to check your Equifax credit score without getting overwhelmed
Start by choosing your purpose, because it changes what you look at first:
- Routine monitoring: focus on trends and obvious changes (big drops, new accounts, new inquiries).
- Preparing for an application: focus on utilization, recent late payments, and anything that could be disputed and corrected before a deadline.
- Investigating a potential issue: focus on unfamiliar accounts, incorrect late payments, or unknown hard inquiries.
As you check, confirm you’re looking at Equifax (not TransUnion or Experian) and note the scoring model if it’s listed. Before you dig into details, record the basics: the score number, the date pulled, and any reason codes or factors shown. If you’re comparing scores from different places, compare the direction (up/down) rather than expecting an exact match.
Understanding the building blocks behind the number
Your score is driven by patterns inside the report. When you’re deciding what to tackle first, these categories are usually where the fastest clarity comes from:
- Payment history: late payments, collections, and how recently an issue occurred can affect results.
- Utilization: how much revolving credit you’re using compared to limits; small balance shifts can move a score.
- Length of credit history: older accounts and average age can support stability.
- New credit: hard inquiries and newly opened accounts can temporarily affect scoring.
- Credit mix: different account types can matter, but it’s not a reason to open accounts you don’t need.
Reading an Equifax credit report: the exact sections to scan first
If you want to get practical quickly, scan in this order:
Common Equifax credit report errors—and what to do next
For official background on credit reports and dispute rights, you can also review the Consumer Financial Protection Bureau’s resources at consumerfinance.gov.
Score ranges, “good” vs. “ready,” and how to set a practical target
A 30-day action plan to stabilize and improve what Equifax shows
- Week 1: Pull your report, list every account, and mark anything unfamiliar or incorrect. (You can access free weekly reports through the FTC’s guidance.)
- Week 2: Bring revolving balances down where possible; set autopay or reminders for every due date.
- Week 3: Dispute errors with clear, specific bullets and documentation; avoid broad “not mine” disputes without details.
- Week 4: Confirm updates, keep utilization steady, and avoid unnecessary new applications while corrections are in progress.
- Ongoing: Keep a simple credit folder with dispute letters, confirmations, and screenshots of report/score dates.
If you want Equifax’s own starting point for consumer tools, visit Equifax’s personal site.
What our digital download includes and how to use it
Our Checking and Understanding Your Equifax Credit Score Guide (Digital Download) is designed to function like a workbook you can reuse: check, note, act, and re-check on a schedule you control.
Other digital downloads our team keeps handy
- Unlock the Page: Your Simple Guide to Getting Motivated to Read More Books (Digital Download)
- Zip It Up: The Ultimate Guide to Styling Your Zip-Up Hoodie Like a Pro (Digital Download)
FAQ
Why is my Equifax score different from what I see somewhere else?
Differences usually come from different bureau data, different scoring models, and different update timing. Compare trends over time and confirm which bureau and model you’re viewing rather than expecting every source to match exactly.
How often should an Equifax credit score be checked?
Monthly is a practical cadence for most people when monitoring or improving credit, plus an extra check before major applications and after disputes are resolved. Daily checks tend to add stress without adding useful signal.
What should be done first if something on the Equifax report looks wrong?
Start by verifying the account details and dates, then gather supporting records and dispute the specific inaccuracies with Equifax while also contacting the furnisher when appropriate. If identity theft is a concern, consider a fraud alert or credit freeze right away.



Leave a comment